Sell My House Fast in Farragut, TN: Your Real Options

If you need to sell a Farragut house quickly, compare a direct as-is offer, an as-is listing and a repair-then-list plan. I would start with your actual deadline and what work you are willing to fund, not a claim that one route always wins. A cash-funded purchase can avoid mortgage approval, but title, access and contract conditions still matter. This guide explains the tradeoffs and the questions to settle before choosing.
Compare the available sale routes. Explore Farragut cash sales
TL;DR
- The source article described Farragut as a balanced market, but the linked page checked October 22 displays September 2026 data and calls it a seller’s market. Its median listing price is $799,250, median sold price $701,000 and median days on market 66. These are area statistics, not your property’s valuation or deadline.
- An agreed direct as-is purchase can avoid seller repairs and a listing-agent commission. Walkthroughs or inspections can still be required. Compare actual net proceeds rather than assuming the cash offer is always the better or worse number.
- Listing makes sense when the house is in good shape and you can wait. A cash sale makes sense when time, condition or complications decide it.
- If you are behind on your mortgage, call your servicer first. A sale is one option among several, and it can beat foreclosure when you have equity.
- Get any offer in writing, ask for proof of funds and never sign a deed over under a lease-back arrangement without an attorney.
Table of Contents
- What “fast” means in Farragut
- Your options side by side
- How to compare net proceeds
- When listing is the better choice
- When a direct cash sale fits
- If you are behind on your mortgage
- Red flags with fast-cash offers
- Our perspective on selling fast in Farragut
- What a direct sale looks like with us
- After you close
- FAQ
- Sources
What “fast” means in Farragut
The provider called its reference Realtor.com’s October 2026 market summary. At our October 22 check, however, that link displayed September 2026 figures: a $799,250 median listing price, $701,000 median sold price and 66 median days on market. I would not apply these townwide numbers to a particular house without comparable sales and a condition review.
Days on market is not a promised time from your first call to money in your account. Data providers use different definitions and reporting windows. Ask a local agent which recent completed sales resemble your property, then ask the closing professional what financing, payoff, title and signing steps remain. Do not add a fixed closing period to an area median and treat the result as your deadline.
So when you search “sell my house fast,” ask yourself which part needs to be fast:
- Getting an offer. Ask when the buyer can complete its review; no response time is guaranteed.
- Getting to closing. Depends on title, your payoff and the buyer’s financing.
- Getting out of the property. Depends on your move, tenants or belongings.
Your options side by side
| Direct as-is cash sale | List with an agent | Fix up, then list | |
|---|---|---|---|
| Typical speed | Potentially shorter; title, funds and contract terms control | Marketing plus the agreed closing process | Allow time for the chosen repairs before marketing |
| Repairs | No seller repairs if agreed in writing | Often negotiated after inspection | You pay up front |
| Showings | No public marketing required; agreed visits may remain | Yes | Yes |
| Commission | No listing-agent commission on a direct purchase | Agent commission, negotiated | Agent commission, negotiated |
| Price | Compare the actual written offer | Open-market exposure; price not guaranteed | Compare sale proceeds after repair and carrying costs |
| Risk of falling through | Cash avoids mortgage approval, not every contingency | Depends on financing, inspections and other terms | Same as listing |
| Best for | Deadlines, damaged or inherited homes, tenants | Owners considering public marketing, including as-is | Projects supported by a realistic budget and timeline |
The National Association of Realtors provides background on direct buying. A buyer may consider condition and comparable sales when pricing a property, but a cash label does not guarantee completion. Compare the actual net proceeds and written conditions for your house.
How to compare net proceeds
A higher listing price does not always mean more money in your pocket. Put both routes on the same page:
- Estimated sale price. For a listing, get an agent’s comparable sales. For a direct offer, use the written number.
- Subtract your mortgage payoff and any liens. Ask your servicer for a payoff letter.
- Subtract selling costs. For a listing: agent commission, repairs the buyer asks for, and carrying costs such as the mortgage, taxes, insurance and utilities every month it sits. For a direct purchase, ask what costs you pay and get them in writing.
- Add up the time. Every month on the market has a cost.
Describing Tennessee transfer tax as 37 cents per $100 of the sale price is shorthand, not the complete tax-base rule. Tennessee Revenue generally uses the greater of consideration or fair market value for a freehold transfer, unless exempt, and identifies the grantee/transferee as the responsible taxpayer. Even so, ask whoever is handling your closing to show who pays each line on the settlement statement before you sign.
Our cash offer calculator compares estimated seller net using your inputs for the different sale routes. It does not estimate your home’s market value or issue an offer. Keep payoffs and seller expenses separate and avoid counting a cost twice.
When listing is the better choice
We buy properties, but a direct offer is not automatically the right choice. If you can accommodate marketing and visits, ask an agent about a realistic as-is listing as well as a prepared listing. Compare actual expected proceeds and work involved. A townwide sale-to-list ratio cannot establish the likely outcome for your home.
Listing also makes sense if you have the budget for small fixes, such as paint, flooring or a service call on an old HVAC system, and the patience to let the market work.
When a direct cash sale fits
A direct sale tends to fit when one or more of these is true:
- You have a closing deadline: a job transfer, a divorce, a new home already under contract.
- The house needs work you cannot or do not want to pay for. Our page on selling a house that needs repairs covers how that works in Knox County.
- You inherited the property and live out of state. Our probate and inherited property guide explains who needs authority to sign.
- You are a landlord with tenants in place, or the house is vacant.
- A previous sale fell apart because of the buyer’s financing, an appraisal or an inspection.
If you are behind on your mortgage
This is the situation where speed matters most and mistakes cost the most, so slow down for one step: call your mortgage servicer. The CFPB says to contact the servicer as soon as you know you cannot pay, because options such as a loan modification or repayment plan may come before a sale. You can also reach a HUD-approved housing counseling agency, which the CFPB says can help at low or no cost.
If you have real equity, a regular sale can leave you better off than foreclosure. The CFPB has noted that a completed foreclosure cost the average borrower around $12,500 in 2021 dollars, including late charges, legal fees and property upkeep. That is a historical national estimate, not a current Knox County quote. A signed purchase contract alone does not halt a foreclosure sale. A short sale, where the price is below what you owe, needs your lender’s approval and is a different route with different consequences.
If you want to run the numbers on your own payoff, equity and holding costs before deciding, the mortgage guides at Real Estate Investor Toolkit explain the financing side in plain terms. For the Tennessee process and timeline, read our foreclosure timeline and trustee sale guide.
We are a property buyer. We are not a law firm, a lender or a foreclosure-rescue service, so for legal questions about your loan, talk to a Tennessee real estate attorney or your housing counselor.

Red flags with fast-cash offers
Speed attracts pressure. A few protections worth knowing:
- Foreclosure rescue fees. The Tennessee Attorney General says foreclosure rescue companies cannot charge upfront fees, and describes written-contract and three-day cancellation protections for covered foreclosure-rescue services. Do not assume that this gives you a general three-day cancellation right on a house purchase contract.
- Recorded service agreements. The Attorney General’s notice labeled here as 2024 Tennessee law describes restrictions on recording service agreements and on specified unfair provisions. The notice was issued in 2024; the underlying act took effect in 2023. Have an attorney review the actual agreement rather than assuming every long-term contract has identical treatment.
- Sale-leasebacks. The FTC warns that these can carry hidden fees and steep rent increases, and to be wary of any buyer who pushes you to act immediately.
- Deed signing. The Knox County Register of Deeds only records documents. It cannot give legal advice or prepare your deed, and it recommends an attorney because small wording errors can change what a transfer means.
A legitimate buyer will give you a written offer, show proof of funds on request, let you take time and be comfortable with you having an attorney or title company review the paperwork.
Our perspective on selling fast in Farragut
I would compare the work and the numbers before choosing a sale route. An as-is direct purchase may avoid seller repairs and a listing-agent commission, but neither a quick offer nor proof of funds removes every closing condition. Ask what can change the price, who will buy and what must happen before closing.
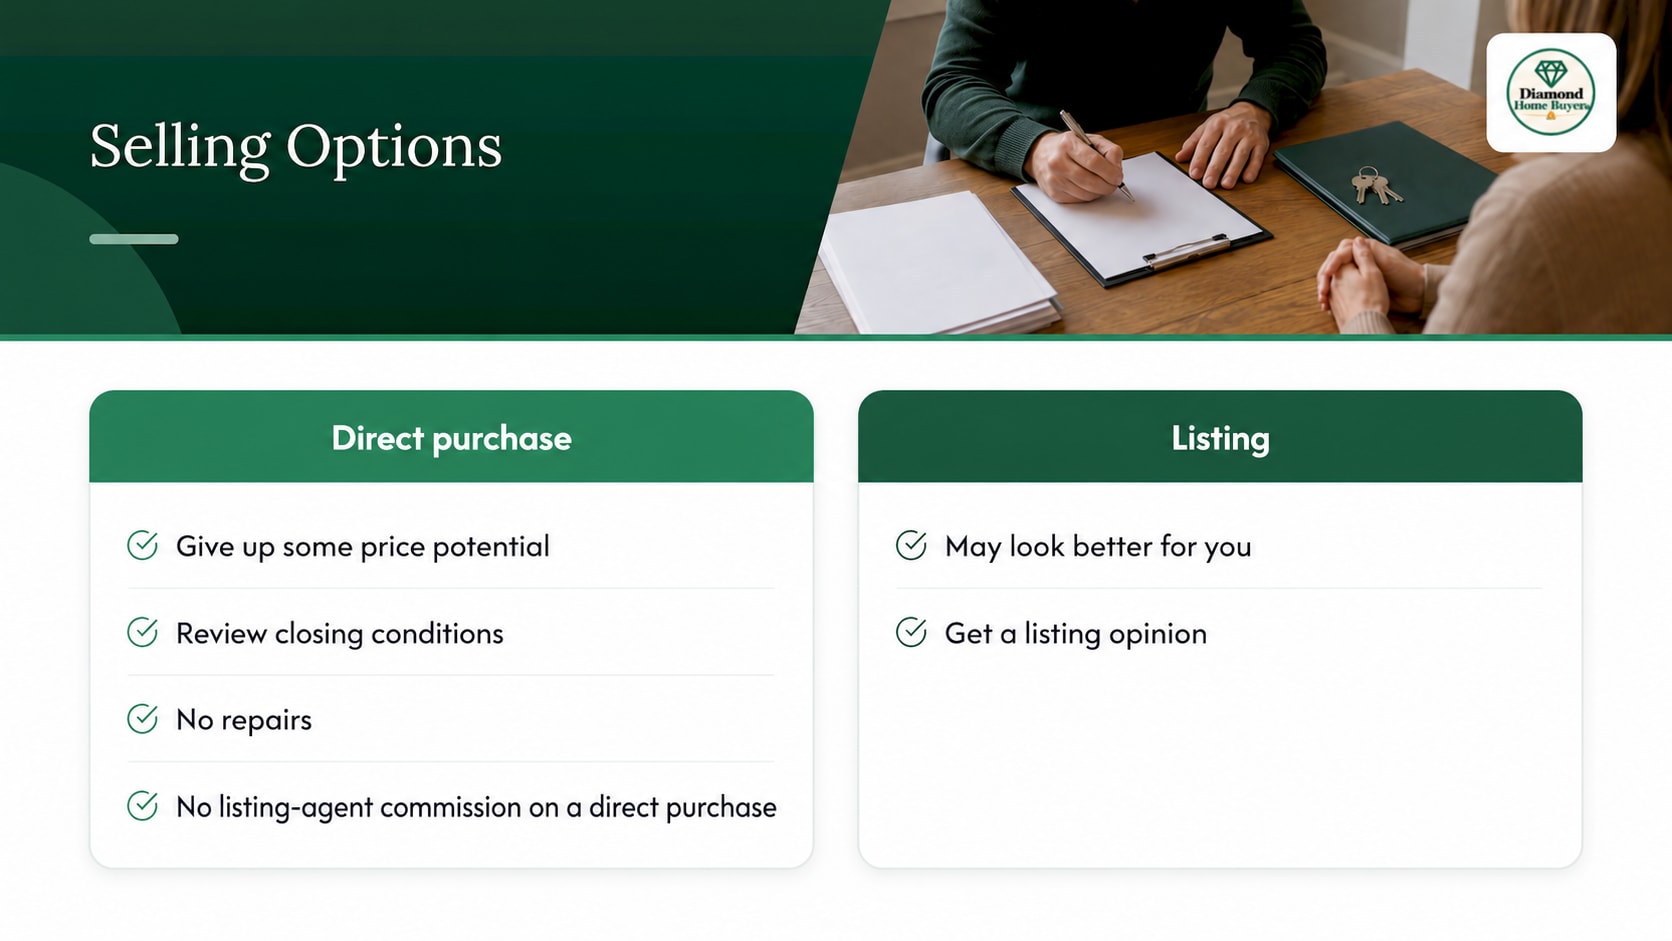
That trade is only worth it if you understand it. So before we make an offer we review the property, the ownership, the condition and what the closing needs. Not every property or situation qualifies, and we will tell you if listing looks better for you. Price, access, costs and closing timing are agreed in writing, and they depend on title and other transaction requirements, so we do not promise a date before we have seen those.
Our advice: get a listing opinion and a direct offer, put both through the net-proceeds steps above and pick the one you can live with.
What a direct sale looks like with us
We focus on Knoxville and Knox County, and we buy houses, rentals, inherited property, mobile homes with land and vacant land as-is. For Farragut owners, the steps are straightforward:
- Tell us about the property and your timeline.
- We review the property, ownership and condition.
- If a purchase is feasible, we provide a written, no-obligation offer. You can ask for proof of funds.
- If you accept, price, access, costs and closing date go into the written agreement.
- Title work is completed and you close.
You can read the full process, see our Farragut page, or request a cash offer and compare it with a listing. If you own land rather than a house, see Tennessee land and acreage.
After you close
Online records do not change the moment you sign. The Knox County Property Assessor says it can take up to a week after a deed is recorded for its system to show the new owner, so seeing your name on the tax record for a few days is normal. The state also sends sales questionnaires whenever ownership changes, including private sales, so a form arriving in the mail is routine.
For a deeper side-by-side with listing, see our guide to cash buyer vs. agent in Knoxville.
FAQ
How fast can I really sell my house in Farragut?
A genuinely cash-funded purchase can avoid buyer mortgage approval. It does not automatically remove inspections, valuations or other conditions. The source’s linked phrase 75 days on the market is not a verified current timeline: the linked page checked October 22 displayed 66 days for September 2026. Your closing date depends on your actual agreement, title, funds, payoffs and possession plan.
Do I have to make repairs before a cash sale?
No, not for a direct as-is purchase from us. We factor the condition into the offer instead. The tradeoff is that the price reflects that condition.
Will I get less than listing?
Compare actual offers rather than assuming a universal discount or saving. A direct as-is purchase may avoid seller repairs and a listing-agent commission, but carrying costs continue until the sale completes and contract conditions can remain. Compare realistic net proceeds under more than one timing scenario.
Can I sell if I am behind on my mortgage?
A sale may be possible, depending on required payoffs, closing expenses, authority and time. Contact your servicer and a HUD-approved housing counselor promptly. If proceeds are insufficient, other funds or the affected creditors’ approval may be needed; a short sale requires lender approval. Obtain legal advice about any scheduled foreclosure.
How do I know a cash buyer is legitimate?
Ask for a written offer, proof of funds and time to have an attorney or title company review everything. Walk away from upfront fees, pressure to sign immediately or any request to transfer your deed before closing.
Sources
- Farragut, TN housing market, Realtor.com
- Direct buying, National Association of Realtors
- Tennessee transfer tax, GreenVue Title & Escrow
- How to avoid foreclosure, CFPB
- Avoid foreclosure help for homeowners, CFPB
- Selling can be an alternative to foreclosure, CFPB
- What is a short sale, CFPB
- Mortgage-related scams, Tennessee Attorney General
- New law on recording service contracts, Tennessee Attorney General
- Sale-leaseback offers, FTC
- Knox County Register of Deeds
- Knox County Property Assessor FAQ
Recommended
- We Buy Houses Farragut TN | Sell As-Is for Cash
- Sell My House Fast Tennessee | As-Is Cash Offers
- Sell My House Fast Tennessee | As-Is Cash Offers
General education, not legal or tax advice. Transfer-tax details: Tennessee Revenue tax-base guidance. Confirm your transaction with the appropriate professionals.