If a trustee sale is scheduled
Contact your mortgage servicer, a HUD-approved counselor, and a Tennessee-licensed attorney immediately. Independently verify the sale date with the trustee. A purchase contract or assistance application does not automatically stop the auction.

If you are behind on your mortgage in Knoxville, you have more options now than you will after a foreclosure sale is advertised. The first call is to your loan servicer and a free HUD-certified housing counselor. If keeping the house is not realistic, selling before the auction can let you control the outcome. Tennessee moves fast, so the sooner you look at each option, the more of them stay open.
This guide walks through the Tennessee timeline, the free help available in Knox County, how to spot a rescue scam, and how a direct as-is sale compares with listing.
Compare a direct sale with listing
Compare the net proceeds, timing and written conditions before deciding whether to sell.
TL;DR
- Tennessee commonly uses nonjudicial trustee sales. Confirm the actual notice and current sale date; there is no universal foreclosure countdown.
- Call your servicer’s loss mitigation department first, then a HUD-certified counselor. Both are free.
- Never pay an upfront fee to anyone promising to stop a foreclosure, and never stop talking to your lender.
- If you decide to sell, compare a listing with a direct cash purchase on net proceeds, timing and what must be fixed. Not every property or situation qualifies for our offer.
Table of Contents
- How fast foreclosure moves in Tennessee
- Step one: call your servicer
- Free local help in Knoxville
- Watch for foreclosure rescue scams
- When selling before the auction makes sense
- Listing vs. a direct as-is sale
- A realistic plan for the next 14 days
- Our perspective
- Talk to us about an as-is sale
- FAQ
- Sources
How fast foreclosure moves in Tennessee
Most Tennessee mortgages are deeds of trust with a power of sale clause. That lets a trustee sell the home at public auction without going through a court, as this Tennessee foreclosure guide explains.
The timeline in plain terms:
- Missed payments. For covered mortgages, federal rules generally prohibit the first required foreclosure notice or filing until the loan is more than 120 days delinquent, subject to exceptions.
- Notice of sale. The trustee advertises the sale and notifies you. Nolo’s Tennessee summary is background reading, not a substitute for the current statute and your deed. Under Tennessee Public Chapter 515, effective July 1, 2025, the general rule requires at least two newspaper advertisements and a publicly viewable third-party online posting for at least 20 continuous days. The initial newspaper publication must be at least 20 days before the sale. Additional requirements or exceptions may apply.
- Auction. The sale takes place as specified in the current notice, which can identify a physical location or an online bidding platform. Verify the actual date, time and method.
The published sale date matters more than an estimated number of months. This page also maintains our Tennessee foreclosure timeline and trustee sale options material; the older source URL redirects here. Verify any postponement directly with the trustee.
Timelines can change if you apply for loss mitigation, file bankruptcy or contest the sale. A bankruptcy or foreclosure attorney can tell you how that applies to your loan.
Step one: call your servicer
Start with HUD’s guidance on avoiding foreclosure: contact the servicer promptly rather than ignoring letters. Ask what assistance is available for your loan and what documents it needs. A discussion is not an approval or a postponed auction; keep track of both the application and the sale date.
What to do on the call:
- Ask for the loss mitigation department by name, not general customer service.
- Explain what changed: job loss, illness, divorce, a death in the family, a rate or escrow jump.
- Ask which options you qualify for: loan modification, repayment plan, forbearance or a temporary payment reduction.
- Ask what the current delinquency status is and whether a foreclosure referral has been made.
- Write down the date, the name of the person and what was promised. Follow up in writing.
For borrowers and servicers covered by the early-intervention rule, the servicer generally must establish or make good-faith efforts at live contact by day 36 of delinquency and provide the required written notice by day 45. Exceptions and repeat-notice rules apply. Tennessee Housing Development Agency (THDA) offers counseling help; do not wait for a letter before calling. See the CFPB early-intervention rule.
Free local help in Knoxville
HUD-approved foreclosure counseling is free. Legal assistance has its own eligibility and availability requirements. These are starting points, not guarantees of funding or representation:
| Resource | What it does | Contact |
|---|---|---|
| THDA foreclosure prevention | HUD-approved counseling and a list of approved counselors | 1-888-HUD-THDA (483-8432) |
| Knox Housing Partnership | Historical agency name supplied in the article; use HUD’s current directory to verify the agency name, services and contact details | Use the current HUD directory contact details |
| Legal Aid of East Tennessee | Civil legal help for qualifying applicants; the provider determines eligibility and availability | (865) 637-0484; confirm current intake arrangements |
Legal Aid’s Knox County office is at 607 W. Summit Hill Drive. Its resources are limited, so it encourages homeowners to reach out as early as possible. A counselor can organize your budget and talk to the servicer for you. An attorney can tell you about your rights, your deadlines and whether the paperwork is correct.
If you or a spouse is on active duty
The federal Servicemembers Civil Relief Act can restrict foreclosure without court approval on a mortgage taken out before active duty. The Tennessee Attorney General’s military guide advises contacting the servicer right away and explaining how service affected your ability to pay.
If back property taxes are part of the problem
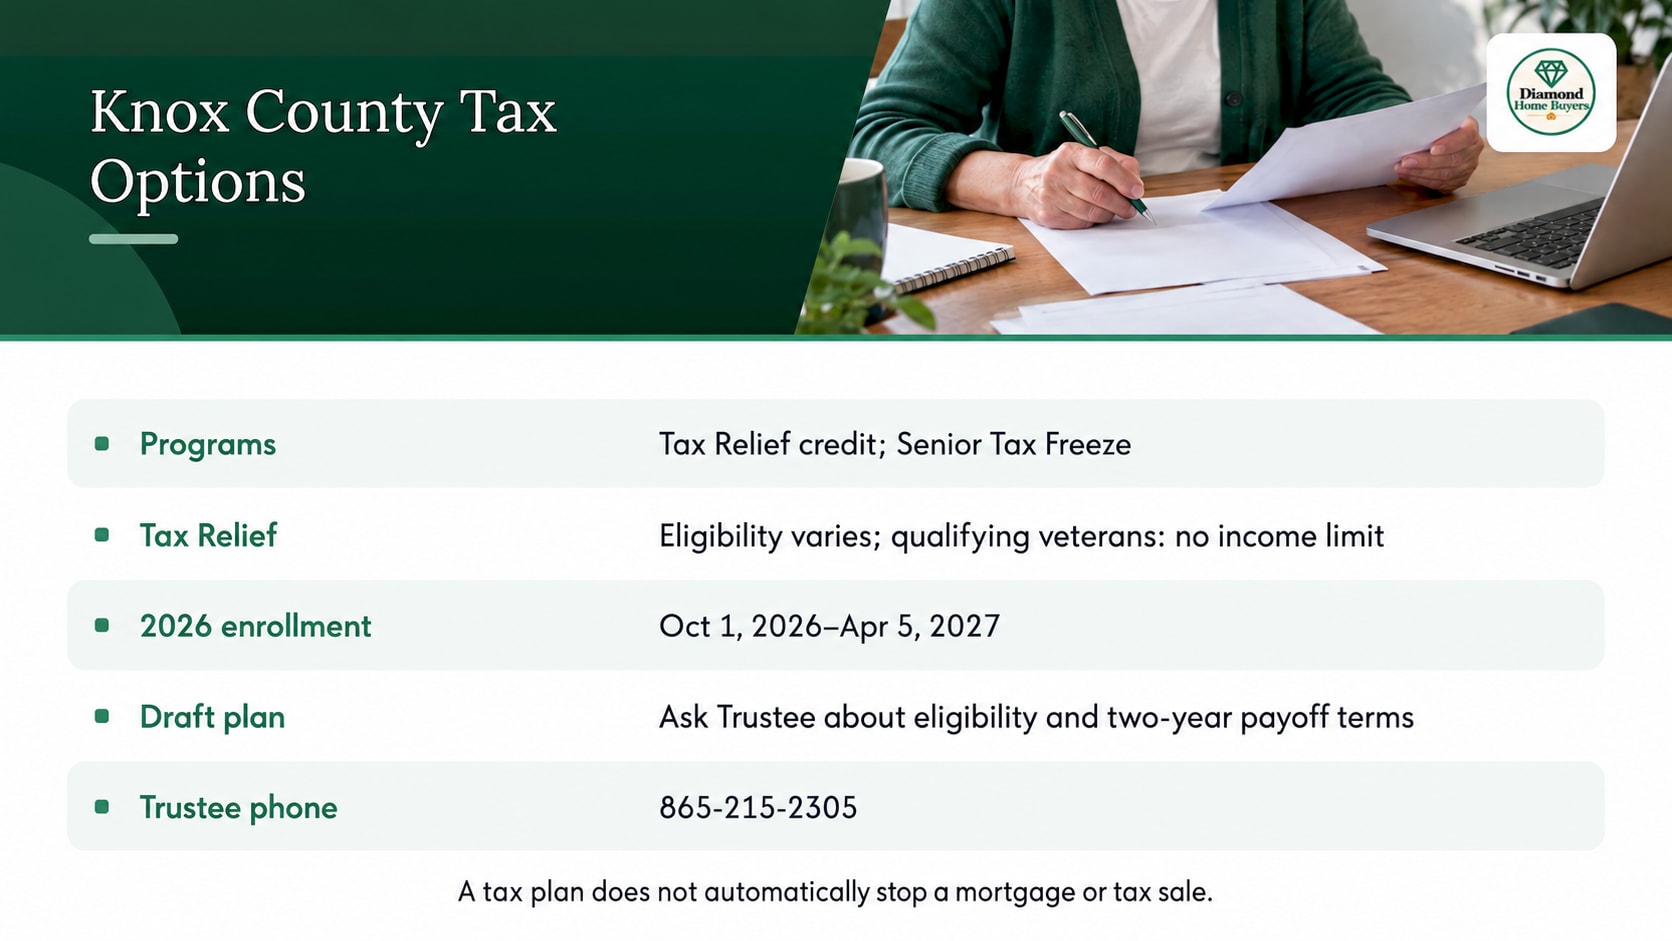
The Knox County Trustee explains Tax Relief credits and Senior Tax Freeze. Eligibility differs by program: qualifying disabled veterans are not subject to an income limit, unlike the elderly and disabled Tax Relief categories. The county lists 2026 enrollment from October 1, 2026, through April 5, 2027 on its current enrollment page. Its separate Delinquent Tax Bank Draft Plan requires a payment amount that pays the total due within two years. Call 865-215-2305 to confirm eligibility and terms. A tax credit, freeze or payment arrangement does not automatically stop a mortgage foreclosure or tax sale.
Watch for foreclosure rescue scams
Homeowners who fall behind often get calls, letters and door hangers within days. The Tennessee Attorney General’s office describes mortgage-related scams that target exactly this moment. Red flags:
- An upfront fee to “stop” the foreclosure. Mortgage-relief services face advance-fee restrictions; exceptions and the nature of the service matter. Have qualified counsel review a proposed agreement rather than assuming a payment buys protection.
- Advice to stop paying or stop talking to your lender.
- Pressure to sign over the deed, or papers you are not given time to read.
- A promise that is too certain.
You have a three-day right to cancel a foreclosure rescue service contract, per the same Attorney General page. If something feels wrong, call Legal Aid or a Tennessee attorney before you sign.
We are a property buyer. We are not a law firm, a tax adviser, a lender, a foreclosure-rescue service or a repair contractor, and we will not tell you to ignore your lender.
When selling before the auction makes sense
Keeping the home is not always possible. A modification may not fit your income. The balance may be larger than you can carry after a job change, a divorce or a death. In those cases, selling before the trustee’s sale can be a sensible way out, because:
- The mortgage is paid from the sale, instead of the home going to auction.
- You can negotiate a buyer and written terms, subject to title, funding, lender requirements and the time remaining.
- Remaining proceeds depend on the actual sale price, valid lien payoffs and closing costs; equity is not a guaranteed payout.
Start with the written mortgage payoff, including its good-through date, then identify taxes, other liens, closing costs and any required approvals. Compare the realistic sale proceeds with all of those obligations—not just the loan balance. Our cash offer calculator compares estimated seller net using the figures you enter; it is not an appraisal, a payoff quote or an offer. A sale that cannot cover the required debt may need lender approval or another arrangement.
Listing vs. a direct as-is sale
There are two main ways to sell on a deadline. Neither is right for everyone.
| Factor | List with an agent | Direct as-is purchase |
|---|---|---|
| Repairs | An as-is listing is possible; financing and negotiated conditions may affect repairs | None required from you |
| Showings | Appointments depend on the marketing plan and property access | Property review instead |
| Agent commission | Typically paid from proceeds | None for a direct purchase |
| Timing | Depends on the market and the buyer’s financing | Agreed in writing, tied to title and transaction requirements |
| Price | Can be higher on a house in good condition | Compare the written price and net proceeds; a cash contract still has conditions |
If your house is in good shape, you have several months before any notice of sale, and you have equity, listing may net you more. If the sale date is close, the house needs work, it is tenant-occupied, or a previous listing or buyer’s financing fell through, a direct sale deserves a place in your comparison. Our guide on cash vs. listing in Knoxville goes through the math.
A few situations come up often with pre-foreclosure sellers, and we have separate pages on them:
A realistic plan for the next 14 days
This is an organizing checklist, not permission to wait. If an auction is scheduled, contact the trustee and a Tennessee attorney immediately. Compress or replace these steps around the actual deadline.
- Day 1: Gather your latest mortgage statement, any default or foreclosure letters, and a list of other liens or unpaid taxes.
- Day 1 to 2: Call the loss mitigation department. Ask about every option and request your payoff in writing.
- Day 2 to 4: Book a free HUD-certified counselor through THDA or Knox Housing Partnership. If you have received a notice of sale, call Legal Aid or a Tennessee attorney the same day.
- Day 4 to 7: Get a sense of your home’s value and your likely net proceeds. Talk to a listing agent if you want that comparison, and request a cash offer if you want that one.
- Day 7 to 14: Decide with the numbers in front of you. Keep every conversation with the servicer in writing.
If a sale date is already advertised, the steps compress. A sale agreement needs time for title work and closing, so say so early to everyone involved. Closing cannot be promised in advance, and some situations simply do not leave enough time.
Our perspective
I would rather you contact your servicer and a qualified counselor first, even if you never request an offer from Diamond Home Buyers. A written list of the amounts, dates and documents can make the next decision clearer. I cannot promise that selling is available or that it will be your best financial outcome.
When a sale is the right answer, our job is to make it a clear one. We review the property, ownership, condition and closing requirements, and then we explain what we can and cannot do. A direct purchase does not require repairs from you or a listing-agent commission, and proof of funds is available on request. Price, access, costs and closing timing are agreed in writing and depend on title and other transaction requirements. Sometimes our offer is not the best route, and when listing or a loan workout fits better, we say so.
Talk to us about an as-is sale
If you are weighing a sale before foreclosure, we can review your Knoxville or Knox County property and give you a written, no-obligation offer to compare with your other options. We also work in Maryville, Alcoa, Oak Ridge, Sevierville, Lenoir City and nearby East Tennessee. Start with our Knoxville as-is cash buying page, or see how we work and who we are. For plain-language definitions, our foreclosure glossary entry is a quick read.
FAQ
How many months before foreclosure in Tennessee?
There is no universal number of months. For covered mortgages, the first required foreclosure notice or filing generally cannot occur until more than 120 days of delinquency, subject to exceptions. Tennessee notice requirements, the deed of trust and the current trustee-sale date govern later steps. Get case-specific advice rather than relying on an online countdown.
Can I sell my house in Knoxville while it is in pre-foreclosure?
Potentially, if there is enough time to clear title, satisfy the mortgage and other required claims, fund and close before the trustee sale. Request written payoff figures and ask qualified professionals to confirm the requirements. A signed purchase contract alone does not postpone the auction.
Is there free foreclosure help in Knox County?
HUD-approved foreclosure counseling is free, and THDA can help you locate counseling resources. Legal Aid of East Tennessee reviews applications for legal help under its eligibility and availability rules. Verify current contact details and seek urgent legal advice if a sale is scheduled.
Do you charge fees or commissions to buy a pre-foreclosure house?
A direct purchase from Diamond Home Buyers does not involve a listing-agent commission or require seller repairs. Mortgage payoffs, liens and any other transaction costs must still be reviewed and agreed in writing. An offer and closing depend on the property, title, contract conditions and available time.
Sources
- THDA: Foreclosure Prevention
- HUD: Avoiding Foreclosure
- Tennessee Foreclosure Process Guide 2026
- Nolo: Tennessee Foreclosure Process and Laws
- HUD housing counseling agencies in Tennessee
- Legal Aid of East Tennessee: Contact Us
- Tennessee Attorney General: Mortgage-Related Scams
- Tennessee Attorney General: Military Guide, Housing Issues
- Knox County Trustee: Property Tax Relief and Senior Tax Freeze
Recommended
- Tennessee Foreclosure Help: Trustee Sale Options
- Sell a Vacant House Fast in Knoxville TN
- Sell a House That Needs Repairs in Knoxville TN
- Sell a Storm-Damaged House in Tennessee | 3 Options
Memphis and Shelby County Foreclosure: A Practical Checklist
A Memphis foreclosure is governed by Tennessee law and the recorded deed of trust, not by a separate Shelby County foreclosure timeline. If a notice identifies a sale date, use that date—not an estimated “Memphis foreclosure timeline”—as the working deadline.
- Verify the sale information. Contact the trustee or substitute trustee named in the notice and confirm the current date, time, location or online bidding platform, and whether the sale has been postponed or cancelled.
- Request written figures. Ask the mortgage servicer or trustee for a written reinstatement amount and payoff statement, including the date through which each figure is valid.
- Start title work early. A voluntary Memphis sale may require mortgage, tax, judgment, HOA, or other lien payoffs. A title company or Tennessee real-estate attorney can identify what must be cleared before closing.
- Use current counseling and legal resources. Contact THDA or HUD-approved housing counseling and seek a Tennessee-licensed attorney for case-specific advice. A pending application or purchase agreement does not by itself cancel the auction.
- Compare net outcomes. If a voluntary sale is still possible, compare written net proceeds and timing—not merely headline prices—and require written confirmation from the trustee when the sale is stopped.
For Memphis property owners comparing a voluntary sale, see the Memphis cash-home-buyer page. Diamond Home Buyers cannot postpone a trustee sale or guarantee that a transaction will close before the auction.
Build a Dated Servicer-and-Trustee Evidence File
A foreclosure call log is more useful when it is tied to the documents that prove what happened. Keep one chronological file and separate the servicer's loss-mitigation review from the trustee's sale notice. They are related, but a statement from one party should not be treated as confirmation from the other.
| Record to keep | What to capture | Question to ask in writing |
|---|---|---|
| Current trustee-sale notice | Sale date, time, method or location, trustee contact, publication details, and any later postponement notice. | What is the current sale date, and has the trustee received written authority to postpone or cancel it? |
| Loss-mitigation intake | The servicer's checklist, date each item was sent, delivery confirmation, upload receipt, and the name or ID of each representative. | Which specific documents are still missing, and what date does the servicer consider the application received? |
| Completeness notice | The written complete/incomplete determination and any later request for corrected or additional information. | Does the servicer consider the application complete for every available loss-mitigation option? |
| Evaluation or denial letter | Options reviewed, decision date, exact denial reasons, acceptance deadline, and any stated appeal right. | Which deadline applies to accept, reject, or appeal this written result? |
| Reinstatement or payoff | Amount, good-through date, payment instructions, permitted funds, and any trustee or legal fees included. | What must clear, and by when, for the trustee sale to be cancelled? |
| Voluntary-sale file | Title commitment, mortgage and lien figures, written offer, proof of funds, settlement estimate, and closing conditions. | Is there enough verified time to clear title, fund, and obtain written sale cancellation? |
Timing changes which federal procedures may apply. Under Regulation X, an application received at least 45 days before a scheduled sale generally triggers a written acknowledgement within five days, excluding weekends and legal public holidays, stating whether it is complete or what is missing. A complete application received more than 37 days before the sale generally must be evaluated in writing within 30 days, and a complete application received at least 90 days before the sale can carry an appeal right for a loan-modification denial. These are federal procedure gates, not promises of approval or of a postponed sale. Use the current rule, the actual notice, and case-specific advice.
Keep the 37-day and 90-day gates in context
The CFPB's consumer guidance says to get a complete application to the servicer more than 37 days before the scheduled sale. If the sale is closer—or the servicer says the file is incomplete—contact the servicer, trustee, a HUD-approved counselor, and a Tennessee-licensed attorney immediately. Continue tracking the sale date unless the trustee confirms a change in writing.
Does Tennessee Have a Redemption Period?
The accurate answer is not simply “no.” Tennessee Code Section 66-8-101 provides a two-year statutory redemption right for specified sales, including a nonjudicial deed-of-trust sale, unless the right is expressly waived in the deed of trust or mortgage. The statute says a waiver of the “equity of redemption” or similar wording can be sufficient.
Many modern deeds of trust contain a waiver, which is why post-sale redemption is often unavailable in practice. But a homeowner should have a Tennessee attorney review the recorded deed and sale documents before assuming there is—or is not—a right to redeem. Tax-sale redemption follows different statutes and should not be mixed with mortgage foreclosure.
Sources used
Tennessee General Assembly: Public Chapter 515 notice changes · Tennessee Commerce: judicial and trust sales · THDA foreclosure prevention · 12 C.F.R. § 1024.41 · CFPB: after a complete application · HUD housing counseling · Tennessee legal-aid directory · Tenn. Code § 66-8-101 text. Original guide references retained; current notice requirements rechecked October 20, 2026.
Additional official guide references
Related Tennessee resources
Compare a no-obligation offer
A contract does not stop an auction. Confirm the deadline and legal options first.
Request a property review or call (865) 339-3213.
General education, not legal, tax or financial advice. Consult a Tennessee-licensed attorney about your loan, notices and deadlines.